
Why Are More Gen Zs Using Credit Cards in the Philippines?
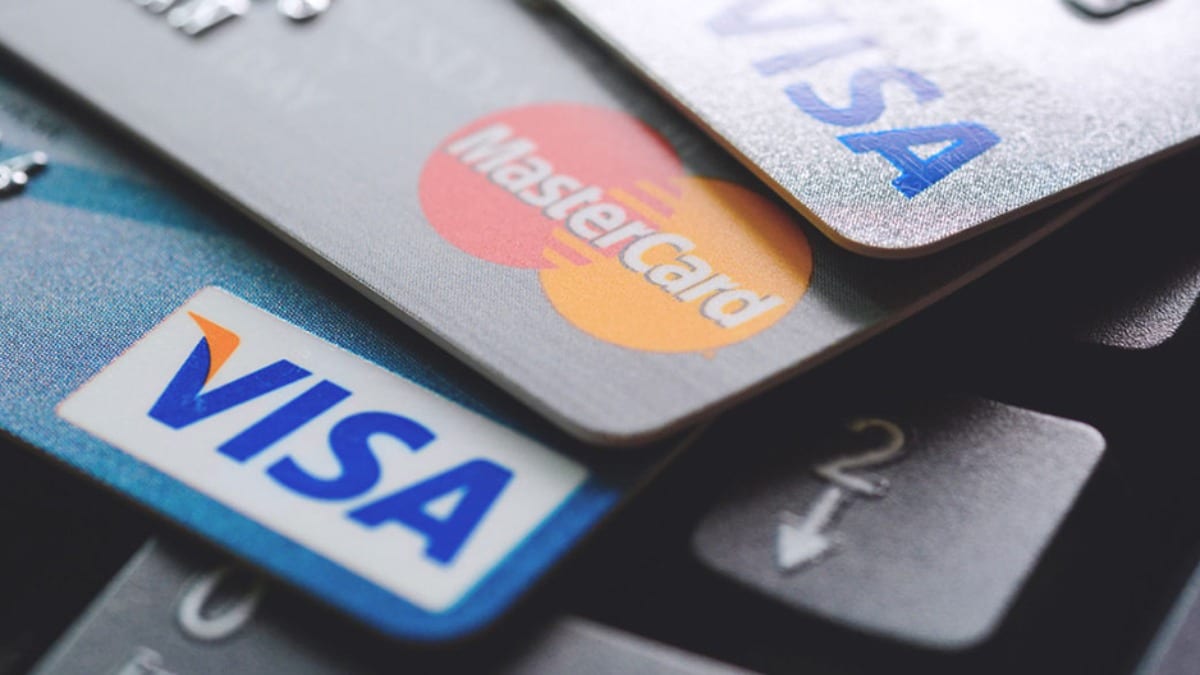
Whether for needs, emergencies, or guilty pleasures, credit cards have long been our spending companion. The modern borrowing tool dates back to the late 19th century, though it wasn’t until the 1950s when it took off. And it's clear that credit cards are here to stay.
Until the end of last year, the number of cardholders in the Philippines has continued to rise, with a significant portion coming from the young adult population. Findings from global information and insights firm TransUnion showed the total outstanding credit card volume was 11.2 million, up from 9.3 million in 2022. The increase is mainly attributed to new borrowers, mostly Gen Zs, who are “quickly emerging as a cornerstone for future market growth.”
“The credit card market in the Philippines will continue to experience growth as demand remains high, especially [among] younger consumers,” Weihan Sun, principal of research and consulting at TransUnion Asia-Pacific, said. “This generation places a higher importance on accessing credit and lending products to achieve their financial goals.”
ALSO READ
Financial Adviser: 5 Proven Ways to Control Your Credit Card Spending
Filipinos Are Spending More Time on Digital Lending Apps, Report Says
The number of Filipino Gen Zs turning to credit cards has more than doubled over the past five years. In 2019, only about 9 percent, or one in every 10 people, used credit cards; the percentage rose to 22 percent by the end of 2023, according to TransUnion. The latest figure is expected to go up as more of these consumers reach adulthood. New-to-card consumers accounted for 30 percent of all outstanding credit card balances, marking a 19-percent increase from the pre-pandemic era five years ago.
Credit card penetration—or the percentage of adults owning at least one credit card—stood at more than 15 percent. Overall, volume and penetration rates grew by around 20 percent. An earlier study from the Credit Card Association of the Philippines (CCAP) also found credit card spending went up by 39 percent to P853 billion in the first six months of last year.
“[Gen Zs] also comprised a greater share of the new-to-card borrowers—[making up] one-third (33 percent) [of the segment] in 2023,” TransUnion said in a statement. “The trends in card origination, volume, penetration, and spending all indicate a promising growth trajectory for the credit card market in the country.”
What’s with the increasing demand?
A lot of factors come into play as to why more consumers are using credit cards nowadays. For one, convenience and flexibility are what make them a preferred payment option for 1.25 billion people in 2023, as cited by Canada-headquartered payment and technology company Clearly Payments. Especially now that cashless payments are the way to go, credit cards are, suffice to say, an integral part of our day-to-day lives.
Here are the other factors influencing the growth of the credit card market:
1| Digital revolution
Nearly all our transactions have gone online these days, regardless of the industry. With this comes the rise of the digital economy which is fueling the demand for credit cards. According to Clearly Payments, retail e-commerce sales hit $4.5 trillion in 2022, with credit cards being the most common payment method. Other in-demand services, besides online shopping, include subscriptions to platforms and consumption of various digital content.
2| Enhanced protection for consumers
While credit cards are not immune to scams and other fraud cases, using reputable brands can offer consumers an added sense of security. These issuers have methods to protect cardholders from unauthorized transactions, including chargebacks, or reversing payments deemed fraudulent or illegal.
3| Rewards and other incentives
What makes credit cards more enticing if not their reward systems? Incentives such as cash backs and other lifestyle perks drive consumers to keep spending and increase their credit limits, ultimately making it easier for them to access more lending products in the future.
4| Long-term credit and financial flexibility
Of course, a good credit history will be beneficial in the long run. In the Philippines, the outstanding level of consumer debt jumped to P1.69 trillion as of November 2023, up from P1.12 trillion in the previous year. This illustrates the significant role credit services, like these plastic cards, play in enhancing financial flexibility.
How credit card providers should take advantage of this trend
Apart from providing more rewards, credit card issuers can tap other value-added services, such as discounts and installment payment facilities, to encourage more consumers to use their products. It may even be better to make these incentives more personalized, catering to different spending habits.
Another key strategy is to utilize the digital-first approach, including allowing online account management, as well as the seamless integration of cardholders’ accounts with e-commerce platforms for the convenience of consumers. The use of virtual cards—which can be enabled with just a tap or a wave of smartphones or gadgets—would be a good idea, too.
“As consumers increasingly seek contactless options for speed and hygiene, the adoption of these payment methods is expected to surge in the future,” Clearly Payments said.
As for security, providing biometric authentication methods, like fingerprint scanning and facial recognition, could help credit card providers attract more borrowers, regardless of their demographic. TransUnion’s study showed male cardholders dominated both the rates of credit card originations and active accounts at around 60 percent each, highlighting “a strong need to focus more on extending financial inclusion among female consumers.”
“Bringing new-to-card consumers into the formal system can drive greater financial inclusion by catering to a larger demographic of borrowers,” Sun said. “Closing the gender gap among credit card borrowers also emerges as a promising avenue for growth. Lenders should consider offerings specifically tailored to female consumers to foster a more financially inclusive credit market, which, at the same time, would help them further capitalize on the growth potential of an expanding market.”
